Getting started
Does Insurance Cover Counseling?
Published 6 min read
By the CGO Clinical Team
Licensed counselors and social workers in Springfield, MO · Meet the team
Staring at your insurance card while trying to decide whether you can afford therapy is a heavy place to be. If you’re asking, does insurance cover counseling, the honest answer is often yes - but not always in the way people expect, and not always for every therapist, service, or plan.
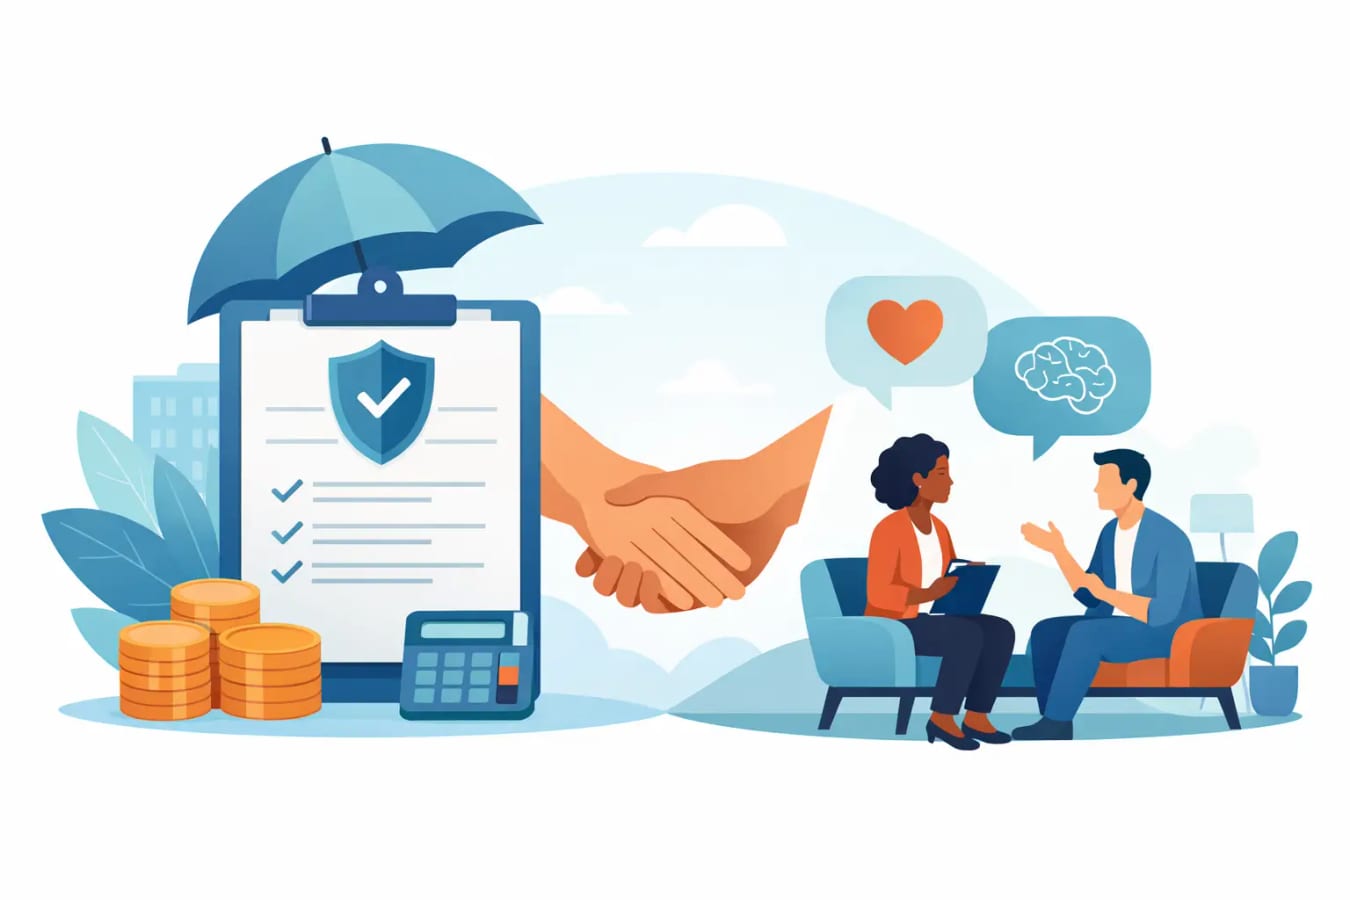
That uncertainty can make it harder to reach out, especially when you’re already overwhelmed. The good news is that many health insurance plans do include mental health benefits, and with a few specific questions, you can usually get a clearer picture of what your out-of-pocket cost may be before your first session.
Does insurance cover counseling in most cases?
In many cases, yes. Most major health insurance plans offer some level of coverage for mental health care, including counseling or psychotherapy. That may apply to individual therapy, couples counseling in some situations, family therapy, and online therapy, depending on the plan and the reason for treatment.
Still, coverage is rarely as simple as “therapy is covered” or “therapy is not covered.” Your cost depends on several moving parts, including whether the therapist is in-network, whether you have met your deductible, whether your plan requires a copay or coinsurance, and whether the service is considered medically necessary under your policy.
This is where people often get tripped up. A plan may technically cover counseling, but if you have a high deductible that has not been met, you could still pay the full session fee until that deductible is reached. On the other hand, some plans offer a fixed copay for outpatient mental health visits, which can make therapy much more manageable.
What insurance usually looks at before it covers counseling
Insurance companies do not all use the exact same rules, but they tend to care about the same basic factors. First, they look at your specific plan benefits. Two people with the same insurance company may have very different mental health coverage because their employers or marketplace plans chose different benefit structures.
Second, they look at provider status. If your therapist is in-network, your insurance company has a contract with that clinician or practice, which usually means lower out-of-pocket costs for you. If the therapist is out-of-network, your plan may still help pay, but reimbursement can be lower, or there may be no coverage at all.
Third, they may look at diagnosis and medical necessity. In plain language, this often means the counseling needs to address a recognized mental health concern such as anxiety, depression, trauma, stress-related symptoms, or another condition that affects daily functioning. That does not mean your pain has to be extreme to deserve support. It simply means insurance plans often want treatment tied to a documented clinical reason.
What types of counseling may be covered
Individual counseling is the most commonly covered service. If you are seeking therapy for anxiety, depression, grief, relationship stress, trauma, life transitions, burnout, or other mental health concerns, insurance is more likely to apply here than in other therapy formats.
Family therapy is sometimes covered, especially when it is connected to a diagnosed client and treatment goals. Coverage for couples counseling is less predictable. Many insurance plans do not cover couples therapy when the focus is the relationship itself rather than an identifiable mental health diagnosis. That can feel frustrating, especially because relationship pain is very real, but it is a common insurance limitation.
Telehealth counseling is also often covered now, though benefits can vary. Some plans cover virtual therapy the same way they cover in-office sessions. Others apply different copays or require the provider to use approved telehealth systems.
Group therapy may be covered as well, though availability depends on the plan and the provider.
Why your therapy bill may still feel confusing
Even when counseling is covered, people are often surprised by the final cost. One reason is the deductible. If your deductible is high, you may pay the full contracted rate for therapy sessions until that deductible is met.
Another reason is coinsurance. Instead of paying a flat copay, you might owe a percentage of the session cost. For example, your plan may cover 80 percent after the deductible, leaving you responsible for 20 percent.
There can also be limits related to session type, length, or provider credentials. Some plans cover services only when delivered by certain licensed professionals. Others require prior authorization for specific levels of care, though standard outpatient counseling often does not need that.
It also matters how a claim is coded. Insurance billing uses diagnosis and procedure codes, and those details affect whether a service is covered and how much the insurer pays. Most clients do not need to understand the billing system in depth, but it helps to know that coverage decisions are based on more than the words “therapy session.”
How to find out if your plan covers counseling
The fastest path is usually to call the member services number on the back of your insurance card. You can also check your insurer’s online portal, but speaking with a person often helps when the language in your plan documents feels vague.
Ask direct questions. You can say that you want outpatient mental health benefits for counseling or psychotherapy. Then ask whether you have a copay, coinsurance, or deductible for those visits. Ask whether telehealth therapy is covered. Ask whether you need a referral from a primary care doctor. And ask what your out-of-network benefits are if you want the option to see a therapist who is not in the plan network.
If you have already found a practice you may want to work with, ask whether they accept your insurance and whether they can help verify benefits. Many counseling practices can give you a benefits estimate, although the final amount owed is still determined by your insurance company.
Questions worth asking before your first session
If insurance is part of your decision, it is okay to be practical. Therapy is personal, but finances matter. You have every right to ask about them.
You may want to ask: Is this therapist in-network with my plan? What will I likely owe per session? Will I be billed a copay, coinsurance, or the full rate until my deductible is met? Does insurance cover online sessions the same as in-person sessions? If I use out-of-network benefits, can I receive a superbill to submit for reimbursement?
These questions do not make you difficult. They make you informed.
If insurance does not cover counseling, you still have options
Sometimes the answer is no. Or the coverage is so limited that it does not make therapy feel accessible. That can be discouraging, especially if it took a lot of courage to start looking in the first place.
If that happens, ask whether the practice offers private pay rates, sliding scale availability, or support with out-of-network reimbursement. Some clients choose to use a health savings account or flexible spending account for counseling expenses. Others decide that paying privately gives them more choice in therapist fit, privacy, or treatment style.
There is no one right way to access care. For some people, using insurance is the best path. For others, private pay ends up being simpler and more flexible.
A note about finding the right fit
Cost matters, but so does feeling safe, respected, and understood. The lowest copay does not always mean the best therapeutic fit. A therapist’s approach, experience, cultural humility, and ability to honor your identity and goals matter deeply.
If you are in Missouri and looking for support, it can help to ask not just whether a practice takes your insurance, but whether they offer the kind of care that helps you feel seen as a whole person. Counseling Group of the Ozarks, for example, centers care around dignity, inclusion, and the reality that every client brings a different story into the room.
If you have been putting off therapy because the insurance question feels intimidating, start smaller than you think you need to. Call your insurer. Call the practice. Ask the awkward money questions. You do not have to have everything figured out before you reach for help. Sometimes the bravest first step is simply finding out what is possible.